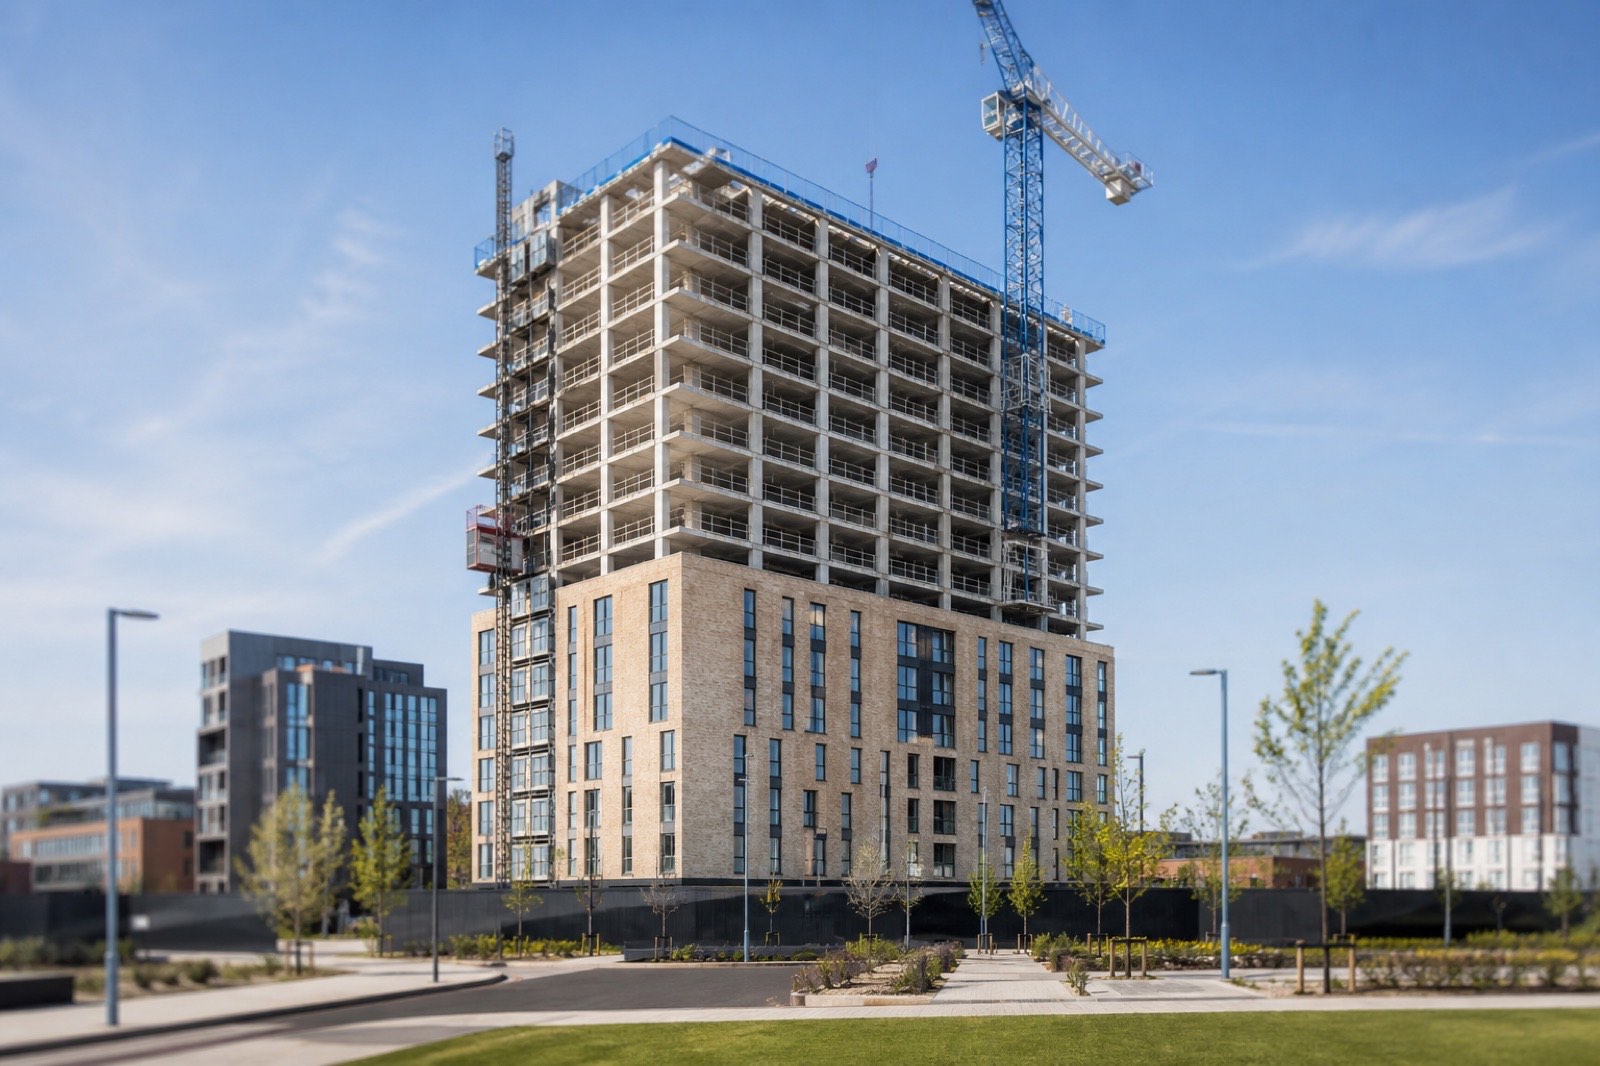
PBSA development finance is a senior construction loan that funds the build of a student scheme, typically at 60 to 70% of cost and capped at 60 to 65% of gross development value (GDV), with interest rolled up. Lenders test demand, planning, delivery, the operator and the exit against the academic year. We arrange PBSA finance and funding; we are not a lender.
What does a purpose-built student accommodation construction loan fund?
Student accommodation development finance is senior secured debt that funds the construction of a PBSA scheme, from site start to practical completion. The lender takes a first charge over the site and the works, releases money in monthly tranches as the build progresses, and is repaid from a sale, a forward funding payment or a refinance once the beds are let.
PBSA development facilities cover part of the land, the build, fees, contingency and interest, which is rolled up or retained because the scheme earns nothing until it opens. Your equity goes in first.
Student accommodation development finance differs from a residential development loan, and from commercial mortgages on let property, in three ways. Value depends on rents, occupancy and the operator. Income arrives by the academic year, so a late finish costs a year of rent. And most schemes are consented as sui generis student housing, so the exit is to a student accommodation buyer or lender, not to flat purchasers.
| Cost line | How lenders treat it |
|---|---|
| Land | Funded as part of total cost, with day-one advance limited by the lender's view of land value |
| Build contract | Funded monthly against quantity surveyor (QS) certified progress |
| Professional fees and statutory costs | Funded as part of cost, including Section 106 and CIL where they apply |
| Contingency | Required by every lender, sized to the risk of the build and higher on complex or tall schemes |
| Finance costs | Interest and fees rolled or retained within the facility |
Treatment varies across facilities and schemes. All lending is subject to status, valuation and lender criteria.
How do lenders size student accommodation development debt?
Lenders size student accommodation development finance on two tests and lend the lower answer. Loan to cost (LTC) measures the facility against total development cost, and loan to gross development value (LTGDV) measures it against the completed, let value from the valuer's report.
Indicative senior leverage runs at 60 to 70% LTC, capped at 60 to 65% of GDV. Which test binds depends on your margin: a scheme with a thin gap between cost and value is limited by GDV, and a scheme with strong land value or a high yield on cost is limited by LTC. Stretch senior and mezzanine facilities can take combined leverage to 80 to 85% of cost where the numbers support it.
A 300-bed PBSA scheme with a total development cost of £40m and a GDV of £50m. At 65% LTC, senior debt would be £26m. At 60% of GDV, it would be £30m. The lower answer, £26m, is the facility, leaving £14m of equity or mezzanine funding to find. Round numbers, not an offer of finance.
GDV for student housing is the capitalised net operating income: rent across 44 to 51 week tenancies, less operating costs, divided by an investment yield. Small movements in any of the three move GDV sharply. Before you approach the market for funding, run your own numbers through our PBSA development appraisal tool.
What do PBSA lenders test before credit approval?
Lenders underwrite student accommodation development finance on five tests, set out in their lending criteria. Each one has to stand up on its own, and a weak answer on any of them reduces leverage or stops the funding.
| Test | What the credit paper asks |
|---|---|
| Demand | Full-time students against PBSA and HMO beds in the city, using HESA enrolment data and UCAS applications; the university's growth, tariff and international share; walking time to campus |
| Planning | A sui generis student consent, the Section 106 occupancy clauses (in England and Wales) and, for higher-risk buildings in England, Gateway 2 approval under the Building Safety Act |
| Delivery | A fixed-price design and build contract, a contractor whose covenant and balance sheet supports the contract, performance bonds and a programme that reaches practical completion before term |
| Operator | Who lets and runs the beds, their occupancy record, the split between direct let and income under a nomination agreement, and operating costs |
| Exit | A forward sale to a student accommodation investor, a stabilisation facility or investment term debt sized on trading figures, and the evidence that it will be there at completion |
Lenders read supply as closely as demand. Knight Frank counts around 19,000 beds under construction for delivery in 2026/27, 95% of them in Russell Group locations, against a ten-year average of about 21,000 new beds a year (Knight Frank, Q2 2026). Lenders use the local pipeline to test whether your PBSA scheme adds to an undersupplied market in London or a strong regional city, or competes with the PBSA schemes next door.
Room mix matters too: studios command higher rents but cost more per bed, while cluster flats suit first-year students and are what most university nominations cover. A nomination agreement on part of the beds can reduce the letting risk a development lender prices in.
Why does the academic year set the timetable for PBSA construction funding?
Students sign for a full academic year. A scheme that reaches practical completion in October has missed its first intake, so it earns little until the following September while interest keeps rolling for another twelve months. That single fact shapes the whole development finance facility: the programme, the contingency, the interest reserve and the term.
Lenders therefore test the developer's build programme against the term date. They expect contingency in time and cost, a contractor with a record of academic-year deadlines, and lettings that start from the January before opening. A programme with slack built in reads far better to a credit committee than one that needs every month to go right.
For tall schemes in England, Gateway 2 now sits on that critical path. Under the Building Safety Act 2022, a building of at least 18 metres or seven storeys with at least two residential units is a higher-risk building, and student accommodation is not among the excluded building types. Construction cannot start until the Building Safety Regulator approves the Gateway 2 application. The regulator reported a median approval time of 22 weeks for new-build higher-risk buildings in June to August 2026, with 92% of applications approved, against 43 weeks and 39% a year earlier (Building Safety Regulator, September 2026).
We build the funding case backwards from the September the beds first let: the Gateway 2 date, the construction start, the drawdown profile, the stabilisation period and the refinance date all key off it. See our guide to the Building Safety Act and Gateway 2.
How is a student scheme development loan drawn down?
Drawdown turns a credit approval for student accommodation development finance into cash on site, in a fixed order.
- 1Equity in firstYour equity, including accepted land value, is spent before the first senior advance.
- 2Conditions precedentFacility agreement, first charge, valuation, the monitoring surveyor's report, the building contract, warranties and, where required, Gateway 2 approval.
- 3Initial advancePart of the land cost and costs to date, within the lender's day-one limit.
- 4Monthly QS certificationThe contractor values the work done, the employer's agent certifies it, and the lender's monitoring surveyor checks it against the programme and the cost plan.
- 5Drawdown requestYou submit the request with the certificate; the lender releases funds and the interest rolls into the loan.
- 6Practical completionThe monitoring surveyor confirms completion, the retention is held under the building contract, and the facility moves into its repayment or refinance period.
Who funds purpose-built student housing schemes in the UK?
The PBSA lending market spans UK commercial banks, specialist property finance lenders, private credit funds active across the living sectors and, at the larger end, institutional forward funders with real estate capital to deploy. We describe it here only from public sources. Shawbrook and Assetz Capital both publicly market student accommodation development finance on their own websites. NatWest provided a £190m green development loan to urbanest for an 897-bed scheme at Albert Embankment, Vauxhall (NatWest, September 2026), and Maslow Capital provided a £116.6m development facility for a 609-bed scheme in Wembley (The Intermediary, February 2026). Naming a lender here describes the market; it does not mean we have a relationship with it.
At the institutional end, Legal & General agreed to forward fund McLaren Property's £160m, 737-bed purpose-built student accommodation scheme on Upper Brook Street, Manchester, in December 2025 (McLaren Property, December 2025). That is the alternative to a construction loan for PBSA projects of that size.
Different lenders and different finance products suit different schemes: some prefer 200 to 400 beds in London and Russell Group cities, some offer facilities only once Gateway 2 is approved, some take development risk only with a named operator. Our part is to match the PBSA scheme to the real estate lenders whose lending criteria it meets and to run a competitive process for the development funding. Our overview of PBSA lenders sets out the market in more detail.
Where senior debt sits in the capital stack, and how it is repaid
Senior development finance ranks first in the capital stack. Above it, a developer can add stretch senior or mezzanine capital to reduce equity, or bring in a joint-venture equity partner. The alternative to the whole debt stack is forward funding, where an institutional investor funds the build and takes the completed asset. We consider every route, because the cheapest capital on paper is not always the right funding for the scheme.
The exit is fixed at the start, not at completion. Most PBSA development finance repays in one of three ways: a sale on completion, often to a forward commitment buyer; a stabilisation facility that carries the scheme through its first letting cycle; or investment term debt, the PBSA equivalent of commercial mortgages, sized on trading income once the beds are let. Bridging finance sits earlier in the sequence: short-term bridging loans fund the site purchase or hold it through planning, and the bridging loan is then repaid from the first development finance drawing.
What should a student scheme funding application include?
A credible student accommodation development finance application answers the five tests lenders consider before they ask. We prepare the credit pack with you, and a complete pack gets indicative terms and capital committed faster.
- Appraisal: land, build, fees, contingency, finance costs, GDV and profit on cost.
- Planning: the decision notice, Section 106 agreement and the Gateway 2 position where the building is higher-risk.
- Build: the contractor, the form of contract, the programme to practical completion and the QS cost plan.
- Market: city demand and supply evidence, the room mix, rents and the income model, whether direct let or nomination.
- Operator: who will run lettings and asset management, with their track record and fee terms.
- Developer: your development record, assets and liabilities, and the source of your equity.
- Exit: the intended sale, stabilisation or refinance route, with evidence.
Every term is subject to status, valuation and lender criteria. Nothing on this page is an offer of finance. PBSA finance of this kind is unregulated commercial lending.
Questions
What does PBSA mean in property?
What is PBSA in the UK?
Who are the top development finance lenders in the UK?
What is PBSA management?
How much deposit do I need for PBSA development finance?
Is PBSA development finance regulated by the FCA?
- Building Safety Regulator, building control approval application data, June to August 2026
- Knight Frank, UK Student Market Update, Q2 2026
- Knight Frank, PBSA investment hits £3.9bn, February 2025
- Knight Frank, Q1 2026 PBSA investment, May 2026
- Building Safety Regulator, building control approval application data, May to July 2026
- Explanatory Memorandum to the Higher-Risk Buildings (Descriptions and Supplementary Provisions) Regulations 2023
- NatWest Group, NatWest backs urbanest for riverside student accommodation, September 2026
- The Intermediary, Maslow Capital provides £116.6m Wembley PBSA facility for YourTRIBE, February 2026
- McLaren Property, funding secured for £160m Upper Brook Street student accommodation, December 2025
- Shawbrook, student accommodation development finance
- Assetz Capital, development finance for student accommodation
 Written and reviewed by Matt Lenzie, Founder and principal. Last reviewed .