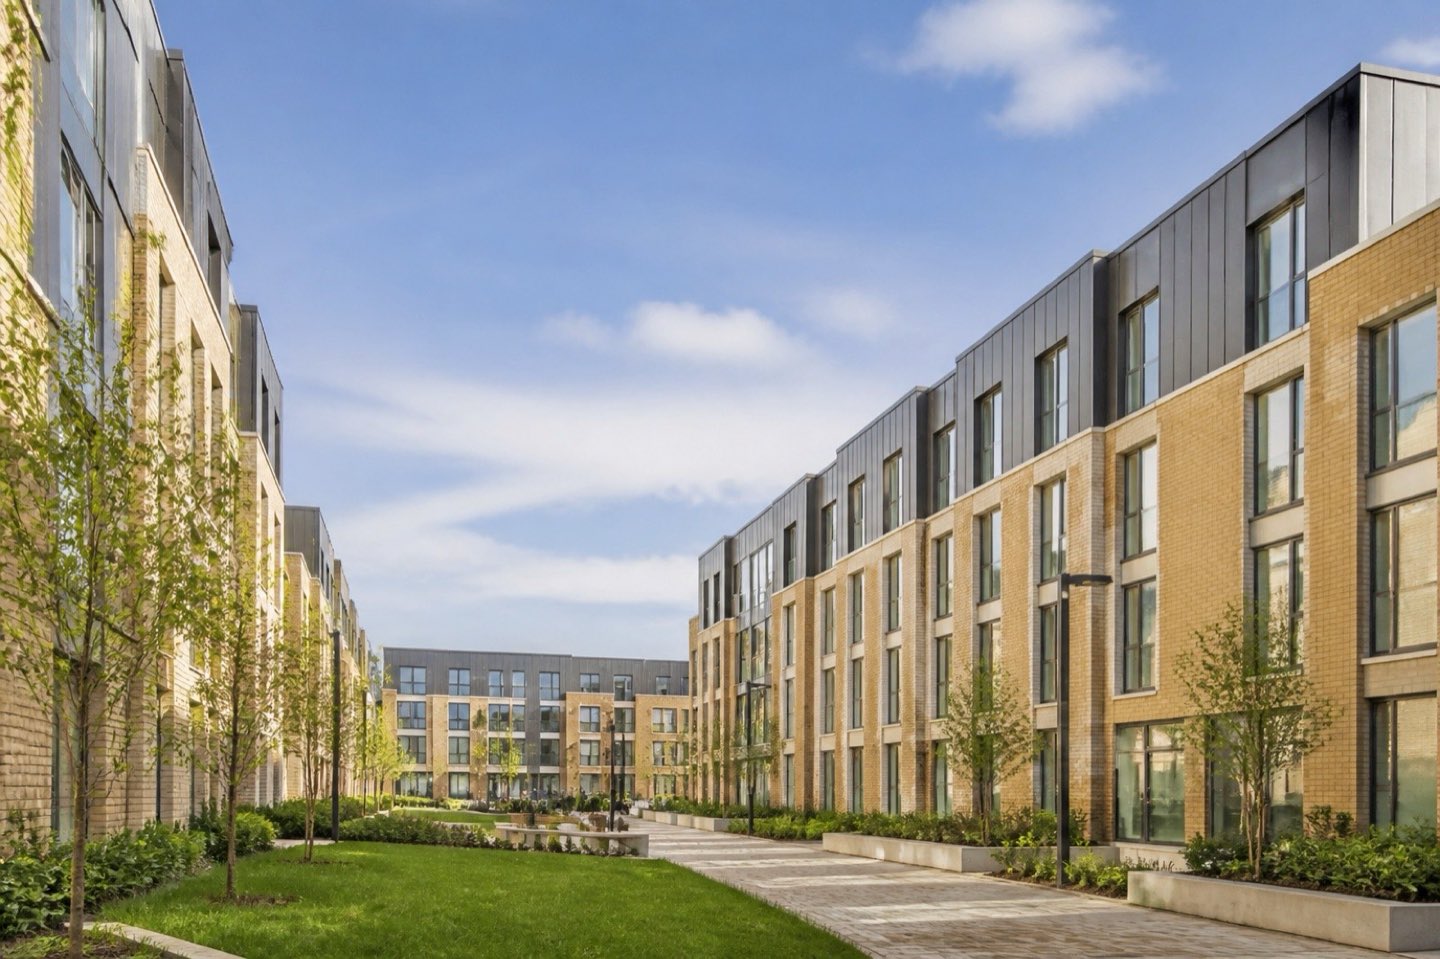
Investment finance is senior term debt secured on a let, trading student accommodation property. Lenders size it on the lowest of loan to value, interest cover and debt yield, typically 55 to 65% LTV over 3 to 7 years. The rent roll, the split between direct let and nomination income, and the operator behind them decide how far each test stretches.
What is acquisition finance for operating PBSA?
PBSA acquisition finance is senior debt secured on an operating student accommodation property. It funds the purchase of a let student property, or refinances one already owned, and it is repaid from the rent the students pay. Unlike development finance, nothing is being built: the lender is underwriting a trading residential property investment with a track record of student lettings.
That changes the credit question. A construction lender asks whether the scheme will be finished and let. An investment lender asks whether the current net operating income (NOI) is real, whether it will hold through the loan term, and what the property would sell for if the borrower failed. The answers come from the rent roll, the booking history across several academic years, the operating costs and the valuation.
Borrowers range from private investors buying a single 150-bed student housing block to institutional funds acquiring portfolios of several thousand beds across England, Scotland and Wales. The finance is the same family in each case: a first-charge property investment loan, usually interest only or lightly amortising, with covenants tested quarterly.
Lenders class PBSA investment as a specialist residential property investment, separate from build to rent and from student HMOs. Rents reset every academic year, so income can grow faster than in other residential investment, but it can also fall faster if occupancy slips. That is why PBSA property investment lending is sized on trading history and development potential is ignored: the loan backs the income the residential property already earns.
Investment finance is stage five of the six-stage PBSA funding sequence. It normally follows stabilisation finance on newly built student housing, or replaces a maturing facility through a PBSA refinance.
How do lenders size a student accommodation investment loan?
Every student accommodation investment lender runs three tests on the same property and lends the lowest answer. Loan to value (LTV) protects the lender against a fall in capital value. Interest cover (ICR) checks that NOI covers the interest bill, at the lender's stressed rate, by a set multiple. Debt yield, NOI divided by the loan, measures how much income backs each pound of debt, whatever interest rates do.
| Test | How it is calculated | When it tends to bind |
|---|---|---|
| Loan to value (LTV) | Loan divided by the valuer's market value | Prime student property bought at low yields, where value is high relative to income |
| Interest cover (ICR) | NOI divided by annual interest, at the lender's stressed rate | When swap rates are high, or the loan is floating and unhedged |
| Debt yield | NOI divided by the loan amount | Regional and secondary student accommodation, or property with a thin operating history |
Indicative. Leverage on operating PBSA runs at 55 to 65% LTV, subject to status, valuation and lender criteria.
The valuer's view of NOI drives all three. Lenders take the gross rent roll for the current academic year, deduct voids, the operator's management fee, utilities, staffing, maintenance and a sinking fund for lifecycle replacement, then compare the result with the prior two or three years. A student property whose operating costs sit well below similar residential schemes gets challenged, because it usually means repairs have been deferred.
Illustrative example
Illustrative example: an investor agrees to buy a 300-bed operating student property for £25m. The valuer confirms £25m and an NOI of £1.4m. At 60% LTV the loan could be £15m. If the lender sets a 10% minimum debt yield for this example, the loan is capped at £14m (£1.4m divided by 10%). Debt yield binds, so the offer is £14m, or 56% LTV, and the buyer funds the balance with equity. Test your own numbers in the PBSA debt sizing calculator.
Pricing is set over SONIA or the swap rate for the term, according to leverage, stage and sponsor. A longer fix, such as five years, costs more to hedge but removes the risk that ICR tightens when rates move over the life of the property investment.
Lenders publicly active in PBSA investment debt include clearing banks, insurers and debt funds. NatWest provided a £110m+ investment facility refinancing three stabilised GSA assets and describes PBSA as "a key growth market of our core real estate strategy" (GSA, October 2024). Nuveen provided a £151m green senior term loan refinancing Urbanest Battersea, 853 beds (IPE Real Assets, May 2025). As a market survey average, the Bayes CRE Lending Report recorded student housing investment loans at a margin of about 275 basis points at about 55% LTV (Bayes Business School, mid-year 2024). That is a historical average across the lenders surveyed, not a rate available to any particular borrower; actual pricing depends on leverage, the asset and the sponsor. Naming a lender here describes the market; it does not mean we have a relationship with it.
Direct let or nomination income: how does the rent roll change the loan?
A nomination agreement is a contract under which a university reserves, and usually guarantees rent on, a set number of beds in a private block. Direct-let income comes from students who sign individually, usually on 44 to 51 week tenancies. Most PBSA investment property carries some of each, and student accommodation lenders treat the two differently.
| Feature | Direct let | Nomination agreement |
|---|---|---|
| Who carries the letting risk | The operator, every academic year | The university, for the nominated beds and term |
| Rent level | Market rent, with growth each year | Often below market, with fixed or indexed uplifts |
| What the lender tests | Occupancy history, booking pace, competing supply | University covenant, unexpired term, break clauses |
| Effect on sizing | Leverage depends on location and track record | Supports ICR and lowers risk for the unexpired term |
A long nomination agreement with a strong university can support leverage on regional student accommodation that a direct-let lender would size cautiously. The lender will read the agreement carefully: the length of the unexpired term, whether the university can reduce the number of beds each year, who pays for voids, and what happens at expiry. A nomination deal with two years left adds far less than one with fifteen.
Direct-let student income needs a record. Lenders ask for occupancy and rent achieved across at least three academic years, the booking curve for the coming year measured from the January UCAS deadline onwards, the mix of first-year, returning and postgraduate university students, and the share of international students. Our guide to nomination agreements and direct let covers the contract terms in detail.
Why does the operator covenant matter to a purpose-built student housing lender?
Student housing is an operational residential asset. The same student accommodation building can trade at very different occupancy under different management, so lenders underwrite the operator almost as closely as the property. They look at the operator's portfolio size, occupancy record across academic years, marketing reach with UCAS applications and international student agents, and the terms of the management agreement.
- The management agreement. Its length, the fee basis, performance tests and whether the lender can replace the operator after a default.
- Code membership. Under the Renters' Rights Act 2025, tenancies granted from 1 May 2026 by a provider in an approved code, such as the ANUK/Unipol Code, can stay outside the assured periodic tenancy regime. That keeps fixed academic-year lettings in place (Unipol, 2026). Lenders now check code membership as a condition. See our Renters' Rights Act guide.
- Building safety. For a student housing building of 18 metres or seven storeys and above, the lender checks registration with the Building Safety Regulator, the accountable person arrangements and any remediation.
- Owner-operator or third party. Integrated platforms such as Unite Students run their own assets. Smaller owners of student property appoint a third-party operator, and lenders compare that operator's record with the scheme's rent roll.
A student housing property moving to a new operator at acquisition is common, and it is financeable. Lenders will ask for the new operator's business plan, the transition timetable, and future assumptions that do not rely on the new operator lifting student occupancy or rents straight away.
How are PBSA portfolio loans structured?
A portfolio facility finances several operating assets under one loan, secured on all of them. It suits an investor buying a multi-city student housing portfolio or consolidating single-property loans. Portfolio debt changes the terms in three ways.
- Diversification. Several cities and higher education institutions spread the student demand risk, which can support better terms than any single asset would get.
- Cross-collateralisation. Every asset secures the whole loan, so a weak student property is carried by strong ones. Lenders test the portfolio LTV, ICR and debt yield in aggregate.
- Release pricing. Selling one property usually means repaying more than its allocated share of the debt, at a premium agreed in the facility, to protect the lender's position on what remains.
Portfolio investments at scale are a feature of the market. Unite Group completed its acquisition of Empiric Student Property on 28 January 2026, adding 7,700 beds across 68 buildings in 22 cities and taking the combined portfolio to 71,000 beds across 29 cities (Unite Group, January 2026). Knight Frank recorded it as a £720m transaction (Knight Frank, Q1 2026).
What does the UK student property investment market look like in 2026?
Institutional appetite for the PBSA sector remains deep, and investors still see opportunities in a growing student housing market where student numbers outstrip PBSA beds. But values have been tested by weaker occupancy in some markets, and the challenges are now priced.
Knight Frank recorded £3.87bn of UK PBSA investment in 2024, up 14% on 2023, across 66 deals. It noted that deal times for stabilised assets were getting longer because of building safety regulation (Knight Frank, February 2025). In the first quarter of 2026 investors deployed £2.1bn, and 65% of transactions were sales of operational assets (Knight Frank, Q1 2026). Activity then slowed to £164m in Q2, taking the first half to £2.3bn, and prime direct-let yields moved out to about 4.75% net initial yield in London and 5.50 to 5.75% for regional prime stock (Knight Frank, Q2 2026).
Investment lenders are most active in the large regional student markets, including Greater Manchester (Manchester), Birmingham, Leeds, Bristol, Liverpool and Newcastle, where deep full-time student demand and a track record of operating schemes give them comparable evidence to underwrite against.
Returns have cooled from their average of recent years. The CBRE UK PBSA Index recorded a 3.4% total return in the year to September 2025. Capital values fell 2.0% and income returned 5.4%. Lower occupancy cut net income by 1.6%, and yields moved out slightly (CBRE, 2025). The sector's resilience through the wider economic cycle is real, but it is not uniform. For investment lenders, this is why NOI is tested on actual collected rent rather than asking rents, and why lenders look at pipeline supply in each city. More on pricing in our PBSA yields guide.
What risks do lenders price into a student block acquisition?
Investment lenders price the specific risks of operating student accommodation, and their covenants are written around them. Any borrower who plans to invest in the sector should expect these questions.
| Risk | What the lender checks | Typical protection |
|---|---|---|
| Occupancy | Occupancy by academic year, the booking curve, new supply with planning consent nearby | ICR and debt yield covenants tested quarterly |
| Affordability | Student rents against the maintenance loan and competing HMO housing | Conservative rental growth in the base case |
| International demand | Share of non-UK students, visa and policy exposure | Stress case with lower occupancy |
| Building safety | Height, cladding, fire strategy, BSR registration | Conditions precedent and remediation reserves |
| Obsolescence | Age, specification, EPC rating, lifecycle spend | Capex reserve or cash sweep |
Student demand data matters most. Lenders read HESA student numbers and UCAS applications and acceptances for the host universities, the ratio of full-time students to PBSA beds in the city, research from Knight Frank, CBRE, Savills and Cushman & Wakefield, and the StuRents pipeline of consented schemes nearby. They also count the houses in multiple occupation (HMOs) competing for the same students. Purpose-built student accommodation within walking distance of a Russell Group campus in an undersupplied city is a different credit from a secondary building where new development is arriving, or where international students make up an unusually high share of demand.
How we arrange acquisition debt for operating PBSA
Acquisition debt for operating PBSA is arranged in five steps, from reviewing the property to completing alongside the purchase.
- 1Review the propertyStudent rent roll, three years of trading accounts, operating costs, the management agreement and any nomination agreement.
- 2Size and structureRun LTV, ICR and debt yield together, and choose between floating debt, a swap or a fixed rate.
- 3Approach lendersTake the case to the banks, debt funds and specialist lenders active in operating PBSA for that city and size.
- 4Compare termsHeads of terms side by side on leverage, pricing, covenants, amortisation and prepayment fees.
- 5Run to completionValuation, building safety and legal due diligence, then completion alongside the purchase.
We are a finance arranger and introducer, not a lender. Every term we put forward is subject to status, valuation and lender criteria. If the purchase must complete before term debt is ready, PBSA bridging finance can fund it first.
Questions
Is PBSA a good investment?
Who are the biggest PBSA providers in the UK?
What is the current state of the UK PBSA market?
What is PBSA in the UK?
How much can I borrow to buy operating student accommodation?
- GSA, GSA secures £110m loan from NatWest for three premium UK assets (October 2024)
- IPE Real Assets, Urbanest secures £151m Nuveen loan (May 2025)
- Bayes Business School, Commercial Real Estate Lending Report, mid-year 2024
- Knight Frank, UK Student Market Update Q2 2026
- Knight Frank, PBSA investment hits £3.9bn (February 2025)
- Knight Frank, UK Student Market Update Q1 2026
- CBRE, UK Purpose-Built Student Accommodation Index: Year to September 2025
- Unite Group, Unite Group completes purchase of Empiric Student Property (January 2026)
- Unipol, Students in private sector purpose-built accommodation (Renters' Rights Act 2025)
 Written and reviewed by Matt Lenzie, Founder and principal. Last reviewed .