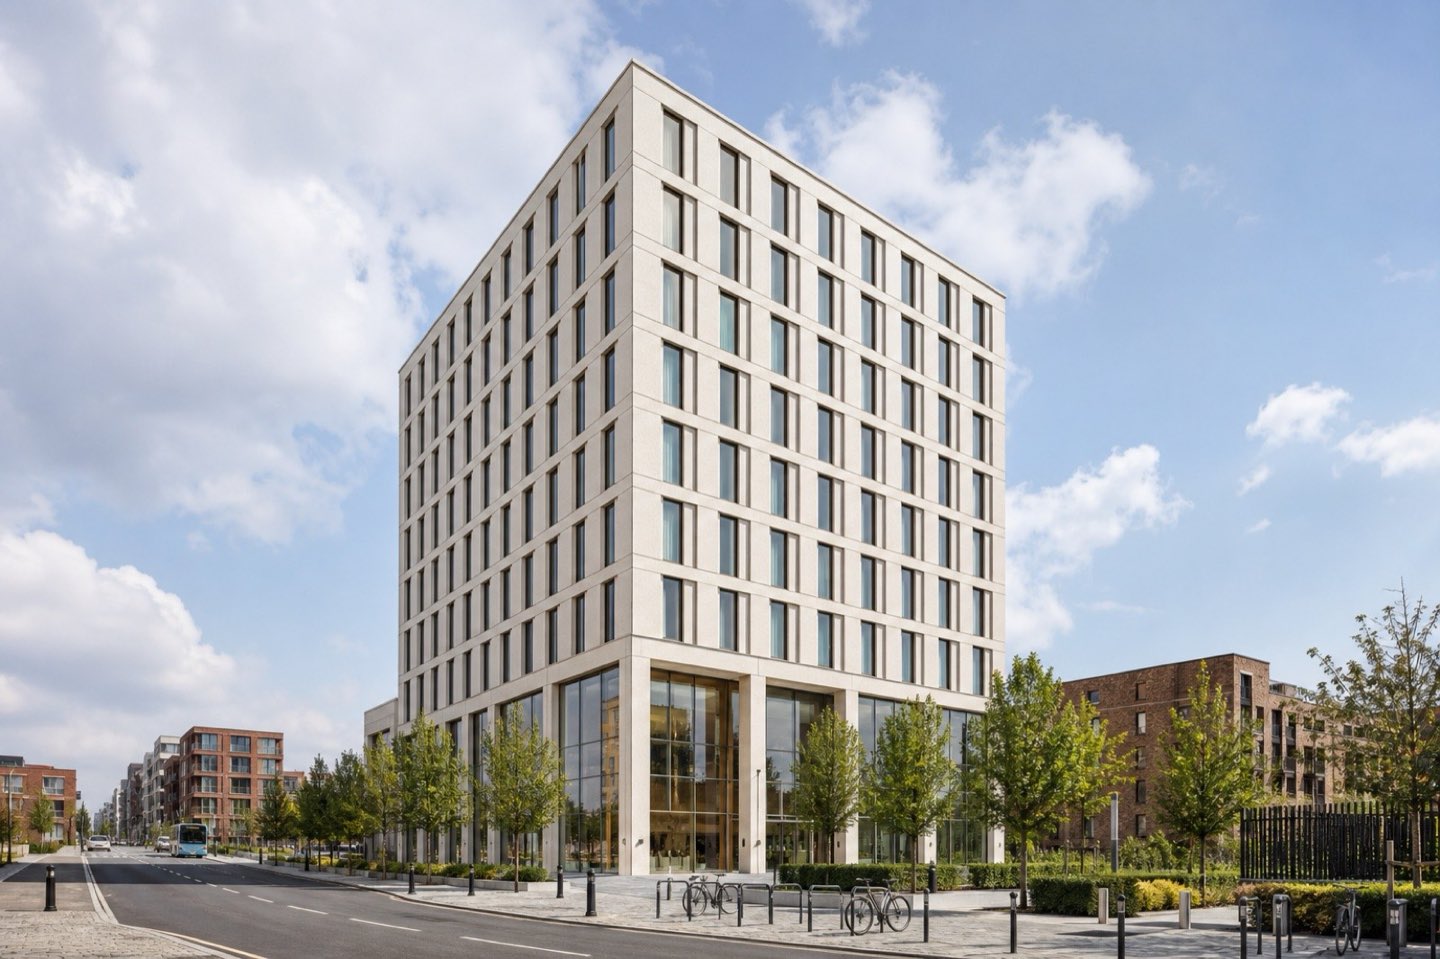
In a forward funding deal the investor buys the site, funds the build month by month and pays the developer a profit on completion, so no construction loan or refinance is needed. In a forward commitment the investor only agrees to buy on completion, and the developer still funds the build. Institutions such as Legal & General have forward funded large student schemes; the trade-off is a lower price than selling a finished, let asset.
What is forward funding in student housing?
Forward funding is a transaction in which an investor buys a development site and funds the construction of a student accommodation scheme, taking ownership of the completed PBSA asset. The developer builds and delivers it under a development agreement and earns its profit when the scheme reaches practical completion, or in stages along the way.
For purpose-built student accommodation (PBSA) it is the institutional route to new stock across the United Kingdom. Pension funds, insurers and real estate investment managers want modern, well-located beds in cities with strong demand, and forward funding lets them buy those beds at a better entry yield than a finished, let scheme would cost. The developer gets its construction capital from the buyer, avoids development debt and a refinance, and fixes its exit before work starts on the project.
The capital is there. Knight Frank recorded £3.87bn of PBSA investment across 66 deals in 2024 and £2.3bn in the first half of 2026, and counts around 19,000 beds under construction for 2026/27 (Knight Frank, 2025 and Q2 2026). Legal & General states that it has more than £1.2bn invested across student accommodation equity and debt (Legal & General, April 2024). Institutions fund new student housing because they want exposure to that market.
What funders are pricing is the income. They look at the room mix (studios against cluster flats), whether beds will be let direct or under a university nomination agreement, and the occupancy the operator can sustain. A studio-led, direct-let scheme can command a keener yield in a deep market but carries more letting risk; a nomination agreement lowers that risk and usually the price. Where a forward commitment is used instead, the developer still needs senior debt to build, so the same questions reach the development lender too.
How does a forward commitment differ from forward funding?
The difference decides who pays for the build. In a forward commitment, the investor agrees today to buy the completed, let scheme at a fixed price or yield, and the developer funds construction itself, usually with development finance. In forward funding, the investor pays for the construction as it happens. A forward sale is simply a contract to sell the building on completion.
| Structure | Who funds construction | Developer risk | Price to developer |
|---|---|---|---|
| Forward funding | The investor, monthly against certified cost | Cost overruns and delivery | Lower: the investor carries the funding and takes an entry yield premium |
| Forward commitment | The developer, usually with development finance | Cost, delivery and funding | Higher: close to the value of a completed, let scheme |
| Forward sale | The developer | Cost, delivery and funding | Agreed price on completion |
General market description. Terms vary by investor and scheme and are subject to contract.
A forward commitment also helps student accommodation development finance: a committed buyer of the PBSA asset at a known price is a strong exit for the development debt, and it can improve the terms on a PBSA development finance facility.
Which institutional investors forward fund PBSA?
Forward funders in the student accommodation sector are institutional investors: insurers, pension funds, real estate investment managers with living sector capital and, occasionally, public-sector landowners. Two public deals show investor appetite in 2025 and 2026.
- Manchester. Legal & General agreed to forward fund McLaren Property's £160m, 737-bed Upper Brook Street scheme of 288 studios and 449 cluster bedrooms, targeting completion for the 2028/29 academic year (McLaren Property, December 2025).
- London. Helical and its joint venture partner Places for London agreed the forward funding of a 429-studio PBSA scheme above Southwark Underground station to a vehicle wholly owned by Places for London, valuing the completed PBSA scheme, which also includes retail space and supports 44 affordable residential homes, at more than £200m. The joint venture receives an initial payment of £35.2m on Gateway 2 approval, returning all equity committed and including an interim profit payment (BE News, February 2026; Clifford Chance, March 2026).
Naming an investor or lender here describes the market; it does not mean we have a relationship with it.
Both deals show what funders look for: a large project in London or a deep regional market near a major university, a strong developer track record and a programme aimed at a specific academic year. Appetite for student accommodation schemes below that scale is thinner, so many smaller developers use development finance with a forward commitment, or build, let and refinance on the rental income.
How is developer profit paid when an institution funds the build?
The investor fixes the total price at the start, usually by applying its target PBSA investment yield to the projected net rental income of the let asset. From that price it deducts the land payment, the build and fee costs it funds, and a coupon: a return on the money it advances during construction. What is left is the developer's profit.
An investor agrees a total price of £50m for a let 300-bed PBSA asset. It pays £8m for the land, funds £36m of build and fees, and charges a £2m coupon on its advances. The developer's profit is the remaining £4m, paid at practical completion, with part sometimes released earlier on milestones such as Gateway 2 approval. If the build overruns, the overrun usually comes out of the developer's profit. Round numbers, not an offer.
Because the investor carries the funding, the developer's profit is usually lower than on a forward commitment or an open-market sale. What the developer gains is certainty of exit, no refinance risk and a far smaller equity requirement. Test the yield on cost that an investor's price implies with our PBSA yield on cost calculator.
What legal agreements sit behind a forward-funded student scheme?
A forward-funding agreement is a package of contracts, negotiated together and conditional on the same milestones.
- Land sale: the investor buys the site, or takes a long lease of it, on exchange or when conditions are met.
- Forward funding agreement: the investor's promise to fund, the payment mechanism, the coupon, the developer's profit and the conditions, such as planning and Gateway 2 approval.
- Development management and building contract: the developer's obligation to deliver to an agreed specification and programme, with a fixed-price contract, warranties and a long-stop date.
- Operator agreement: the management contract or lease with the student operator, and any nomination agreements where part of the income is backed by a university.
- Completion and income: the definition of practical completion and, in some deals, a rental guarantee or top-up while the first academic year lets up.
For higher-risk buildings in England, Gateway 2 approval from the Building Safety Regulator is now a standard condition. Our guide to the Building Safety Act and Gateway 2 explains the timing.
Forward funding or development finance: which suits your scheme?
| Point | Forward funding | Development finance, then refinance or sale |
|---|---|---|
| Equity needed | Low: the investor's capital funds land and build | 30 to 40% of cost at 60 to 70% LTC, less with mezzanine |
| Exit | Fixed at the outset | A sale, stabilisation or refinance at completion, at the market of the day |
| Profit | Lower, but certain | Higher, but exposed to yields and lettings |
| Scheme size | Suits larger schemes in deep markets | Works across sizes and cities |
| Control | Shared: the investor approves design and operator | Developer keeps control |
Indicative, general description. All funding is subject to status, valuation and investor or lender criteria.
We look at the whole capital stack for most schemes: forward funding, senior development debt and mezzanine. Where forward funding is not available, or the price is too low, development finance followed by stabilisation finance and a refinance onto investment debt can keep more of the value, and more equity, with the developer.
How do we take a student scheme to forward funders?
Our forward funding process takes a consented student scheme from a credit-ready pack to a signed funding agreement with an institutional investor.
- 1Test the schemeAppraisal, planning, room mix, rents and operator, against what funders are buying.
- 2Prepare the packDemand evidence, cost plan, programme and income model.
- 3Approach fundersA confidential approach to investors whose appetite and capital fit the scheme's size, city and timing.
- 4Agree heads of termsPrice or yield, coupon, profit, conditions, long-stop date and the operator arrangements.
- 5Due diligence and exchangeLegal, technical and valuation work, then a conditional exchange.
- 6Build and completeMonthly funding, practical completion before term and handover to the investor.
Questions
What does forward funding mean?
What are the key differences between forward funding and forward commitments?
Is forward funding a real loan company?
Who are the biggest PBSA providers in the UK?
Is forward funding regulated?
- McLaren Property, funding secured for £160m Upper Brook Street student accommodation, December 2025
- BE News, Helical and Places for London agree forward-funding deal on Southwark PBSA scheme, February 2026
- Clifford Chance, advises Helical and Places for London JV on disposal of Southwark PBSA, March 2026
- Knight Frank, PBSA investment hits £3.9bn, February 2025
- Knight Frank, UK Student Market Update, Q2 2026
- Legal & General, launches student living platform, April 2024
- Unite Group, Unite Group completes purchase of Empiric Student Property, January 2026
- Kirkland & Ellis, Blackstone's £4.66 billion acquisition of iQ Student Accommodation, 2020
 Written and reviewed by Matt Lenzie, Founder and principal. Last reviewed .