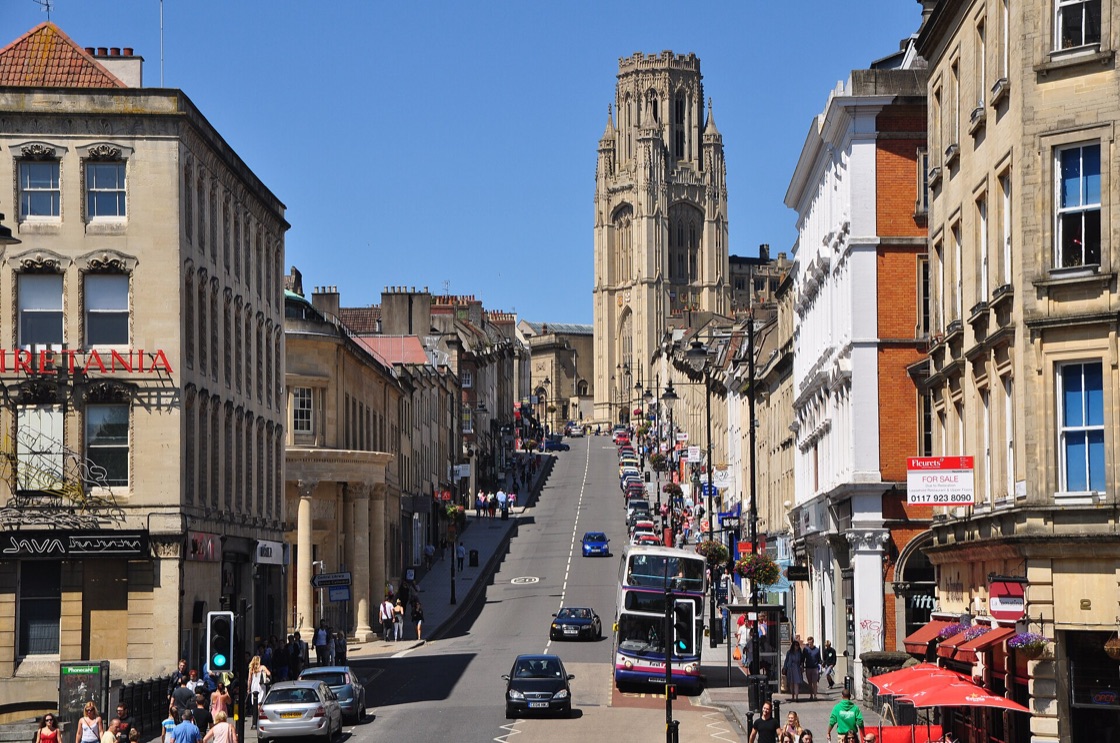

Bristol has one of the UK's highest ratios of students to purpose-built beds and was the second-largest construction market for new student beds at the end of 2025. But the draft Local Plan caps bedspaces in the areas where most schemes are going, one large scheme has been mothballed, and new Article 4 areas take effect in 2027. Lenders want to see where a scheme sits against the cap and the pipeline.
What is in the Bristol, UK student housing pipeline?
12 purpose-built student accommodation applications were lodged in the 12 months to H1 2026: 3 approved and 8 pending. Applications that state a bed count total 614 beds. Over the same period, 95 applications sought to convert homes into student HMOs.
614 beds stated in applications · 1 cell = 1 bed
Source: council planning exports, classified by us. Individual case references are withheld. Applications, not completions.
City-level detail, including sales in the student postcodes and lending by type of lender, is in the H1 2026report on our sister site: Bristol student accommodation report. For the national picture and trends, see the UK PBSA market report, H1 2026.
Why is student demand so deep in the City of Bristol?
Two universities anchor the Bristol student market. The University of Bristol, a Russell Group university, sits in the Clifton and Cotham precinct and is building its new Temple Quarter Enterprise Campus beside Temple Meads. UWE Bristol is based mainly at Frenchay, on the northern edge of the city in South Gloucestershire. The panel shows approximate HESA counts; the more useful local figures come from the council's own evidence.
Unite's planning consultants, citing Bristol City Council's Housing Needs Assessment, put the number of students at Bristol institutions at 59,400 in 2023 against about 16,500 student bedspaces, around 3.6 students per bedspace, with student numbers projected to reach about 65,900 by 2030 (ROK Planning for Unite Group, March 2025). Savills put Bristol's ratio at 3.5 full-time students per PBSA bed, third highest of the 20 markets it studied behind Glasgow and London (Savills, April 2024). Either way, most students still live in shared houses, not purpose-built student accommodation, and both universities' housing policies push first-years toward halls and private schemes.
Where do new student schemes go across Greater Bristol?
New student accommodation in Bristol is concentrated east and south of the centre, on former industrial land around Temple Meads, while the older student neighbourhoods around the University of Bristol are protected by HMO controls and see mainly conversions.
Temple Quarter
The largest cluster of consents, close to the new Temple Quarter campus and the transport hub at Temple Meads. Unite Students' Avon Point on Feeder Road (636 bedspaces under construction as at March 2025) is now letting for 2026/27, from £258 a week (Unite Students, accessed September 2026). Cubex Land and Alara Investments' 22-storey, 530-bed 35 Albert Road secured planning and Gateway 2 approval and was targeting the 2026/27 academic year (UKREiiF, January 2026). Not every scheme has gone ahead: Unite's 500-bed Freestone Island was reported in April 2026 as indefinitely mothballed (HEPI, April 2026).
Bristol city centre
Near Cabot Circus, the retail core of the city centre is becoming a student living location, with shops, transport and social life on the doorstep. Hammerson's Cabot Gate on Dale Street, a 600-bed scheme of part 10 and part 28 storeys designed by AHMM, won outline consent on a 7 to 2 committee vote in April 2026, with reserved matters still to come (Architects' Journal, April 2026).
Bedminster
South of the river, mixed schemes combine student beds with housing. Apsley House's Princess Street scheme, with 400 student beds alongside 434 flats in blocks of 6 to 23 storeys, was approved subject to conditions including 20% affordable housing (Architects' Journal, April 2026).
Clifton, Cotham and Redland
The historic student heartland around the University of Bristol precinct, where Article 4 directions have applied since 2011 and 2012. New supply here comes through conversions: College House on College Green was approved for 57 postgraduate-focused studios for Empiric Student Property (Rapleys, July 2025).
Frenchay and Stoke Gifford
UWE Bristol's main campus sits outside the city boundary in South Gloucestershire, so schemes aimed at UWE students face a different planning authority and a more suburban, transport-dependent market.
How does planning in Bristol, England treat student housing?
The draft Bristol Local Plan 2022 to 2040 introduces Policy H7, which caps PBSA bedspaces in defined areas. At examination, Unite argued that by the council's own figures 4,208 bedspaces had already been consented against a proposed cap of 4,600 in the St Philip's Marsh area (ROK Planning for Unite Group, March 2025). A new scheme there has to show it fits within whatever headroom remains when the plan is adopted.
HMO control is tightening at the same time. New Article 4 directions covering parts of Brislington, Frome Vale, Purdown, Southmead and Horfield, St George and Westbury Park will require planning permission for a house to become a small HMO from 1 January 2027, adding to earlier directions across central and north Bristol (Bristol City Council, accessed September 2026). Fewer new HMOs usually means more demand for managed, purpose-built rooms.
Towers such as Cabot Gate and 35 Albert Road are higher-risk buildings, so Gateway 2 approval under the Building Safety Act is on the critical path. See our guide to PBSA planning and use class.
How do we fund a student scheme in the West of England?
We arrange every stage, from site bridging through construction to investment debt. In Bristol, lenders tend to focus on four things:
- Policy headroom: where the site sits against the draft H7 caps, and whether consent is secure before the plan is adopted.
- Competing supply: Bristol had around 5,000 PBSA beds under construction at the end of 2025, second only to London (Knight Frank, February 2026). Lenders compare your rents and room mix with that wave, not just today's stock.
- Viability: Unite said in July 2026 that weekly rents now need to be above £300 to make new development viable outside London (Unite Group, July 2026). A mothballed scheme in the city shows what happens when the numbers do not work.
- Exit: who buys, forward funds or refinances the scheme at completion.
What do rents mean for PBSA in South West England's largest city?
StuRents live listings show average advertised PBSA rents of around £207 per person per week, against about £136 across all student properties excluding bills (StuRents, accessed September 2026). That rent premium is what a new scheme's room types, location, study spaces and social amenity have to justify against shared living in a house. We found no Bristol-specific occupancy figure for 2025/26; across the wider sector, occupancy averaged around 86% (Unite Group, February 2026), so lenders rely on each operator's own bookings.
For valuation, Knight Frank puts regional prime direct-let yields at around 5.50 to 5.75% (Knight Frank, Q2 2026). Nearby markets behave differently: see Bath, Exeter and Cardiff.
Questions
What is classed as purpose-built student accommodation?
Does Bristol limit new student accommodation?
Is purpose-built student accommodation in Bristol a good investment?
Where are Bristol's new student schemes being built?
- ROK Planning for Unite Group, Bristol Local Plan examination hearing statement, Matter 7, March 2025
- Savills, UK cities need much higher rates of student housing delivery, April 2024
- Unite Students, Avon Point, Bristol (accessed September 2026)
- UKREiiF, £150m student accommodation scheme in Bristol secures planning and Gateway 2 approval, January 2026
- HEPI, Weekend reading: what's happening with the UK's student accommodation?, April 2026
- Architects' Journal, AHMM's 28-storey Bristol student tower scheme clears first hurdle, April 2026
- Architects' Journal, Controversial Bristol housing plans approved, April 2026
- Rapleys, Bristol student accommodation planning approved, July 2025
- Bristol City Council, Restrictions on permitted development: Article 4 directions (accessed September 2026)
- Knight Frank, UK Student Market Update Q4 2025, February 2026
- Unite Group, Interim results for the half year to 30 June 2026
- Unite Group, 2025 full-year results statement, February 2026
- StuRents, Student Accommodation Bristol (live listings, accessed September 2026)
- Knight Frank, UK Student Market Update Q2 2026
- HESA, Higher Education Student Statistics 2023/24 (approximate city counts)
 Written and reviewed by Matt Lenzie, Founder and principal. Last reviewed .