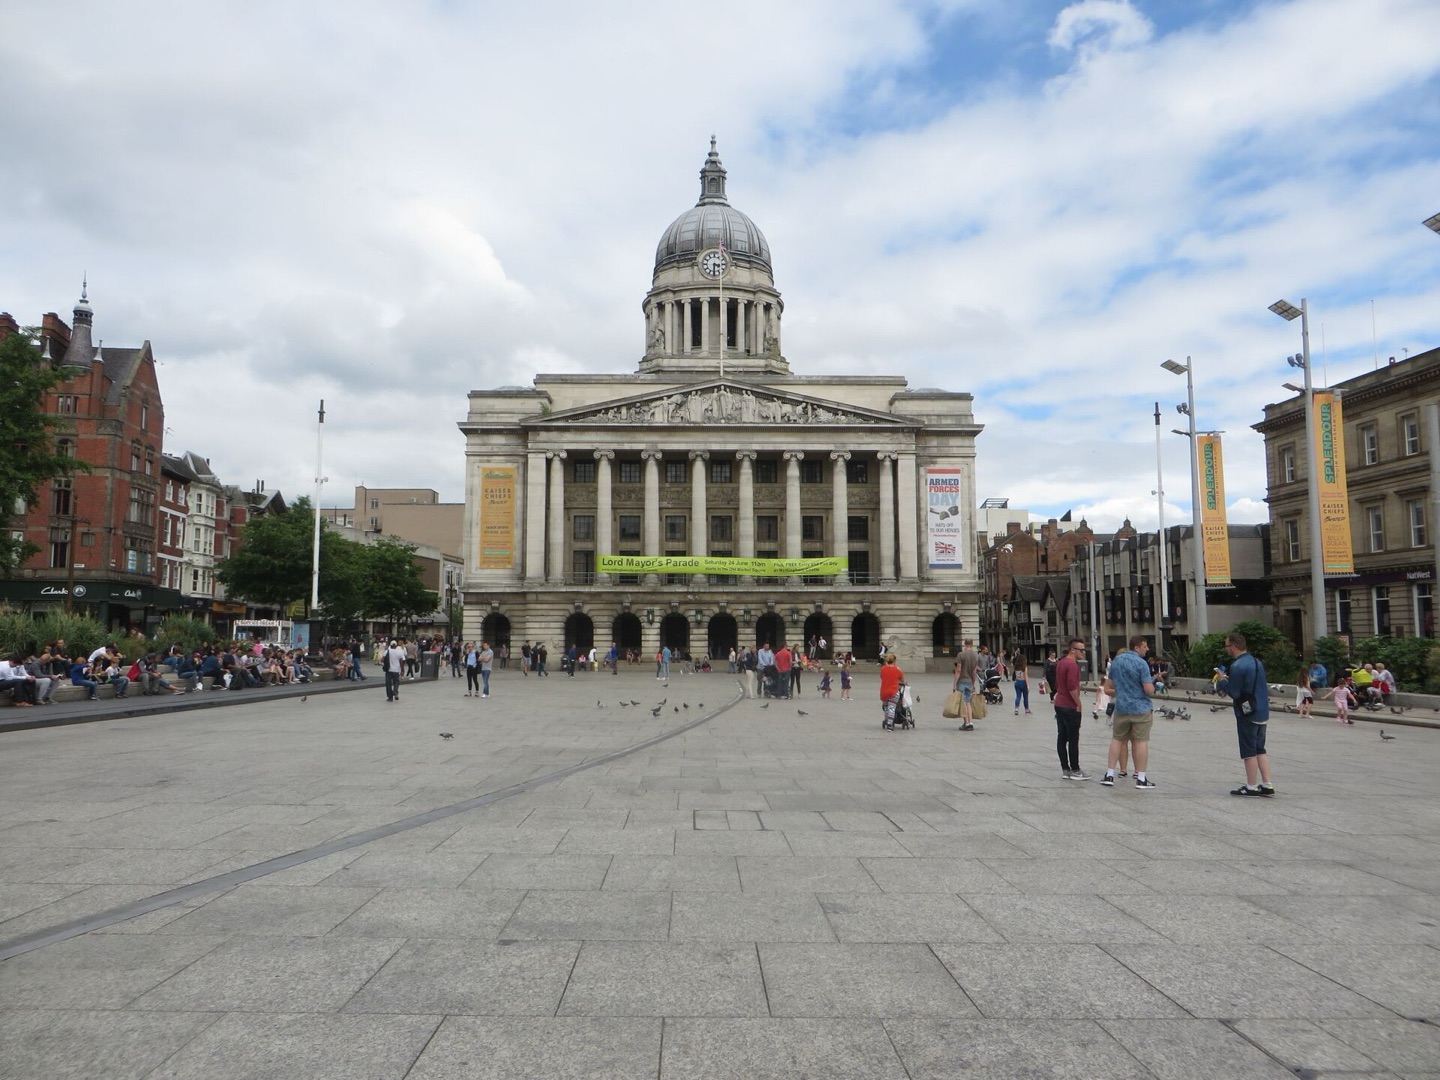

Nottingham built faster than its student numbers grew. Vacancy in the city's purpose-built stock rose from under 1% in 2022/23 to 12.7% in 2025/26, and the cheapest rents fell. Finance is still available, but lenders size it on actual occupancy, favour cluster flats over studios, and want a clear case for why a scheme will let.
What is in the Nottingham student bed pipeline?
5 purpose-built student accommodation applications were lodged in the 12 months to H1 2026: 4 approved and 1 pending. Over the same period, 23 applications sought to convert homes into student HMOs.
Source: council planning exports, classified by us. Individual case references are withheld. Applications, not completions.
City-level detail, including sales in the student postcodes and lending by type of lender, is in the H1 2026report on our sister site: Nottingham student accommodation report. For the national picture and trends, see the UK PBSA market report, H1 2026.
Is Nottingham, UK oversupplied with student accommodation?
Nottingham is oversupplied with student accommodation for now, on the published evidence. Nottingham City Council's March 2026 update counted 36,334 PBSA bedspaces in the city against 53,888 full-time University of Nottingham and Nottingham Trent students, of whom 41,314 need accommodation in the city. Across Greater Nottingham, including Broxtowe, there are about three PBSA beds for every five students (Nottingham City Council, March 2026).
The council's own occupancy survey of 90 schemes with 28,937 beds found 12.7% of beds vacant in 2025/26, up from 11.2% in 2024/25, 3.5% in 2023/24 and 0.8% in 2022/23. Studios fared worst at 16.1% vacant, against 11.6% for cluster flats (Nottingham City Council, March 2026).
Martin Blakey, writing for HEPI, calculated that demand for first-year undergraduate accommodation in Nottingham fell from 46,295 beds in 2022/23 to 42,290 in 2025/26, while more than 7,700 new PBSA beds were added. That was 13.8% of all new-build beds in the UK over the period, and he noted that "all analysts have flagged over-supply" in the city (HEPI, April 2026). Unite Group reported its 2025/26 vacancies were concentrated in Leicester, Nottingham and Sheffield (Unite Group, 2025 results), and Knight Frank recorded marginal rent declines in Nottingham for 2025/26 (Knight Frank, Student Accommodation Outlook 2025/26).
What is happening to student rents in Nottingham, England?
Unipol data cited by the council shows the PBSA rent range for 44-week lets moving from £135 to £330 a week in 2025/26 to £110 to £310 a week for 2026/27. The cheapest room fell 19%. The cheapest studio is from about £160 a week and the cheapest city-centre en suite from about £125 (Nottingham City Council, March 2026). These are ranges, not averages, and no independent average for 2026/27 has been published.
For a lender, falling entry rents matter more than the top of the range. Older and secondary blocks now compete on price with new stock. Nationally, Knight Frank found incentives averaged 4.2% of rent in 2025/26 (Knight Frank, Student Accommodation Outlook 2025/26). A valuation that assumes last year's rent roll and full occupancy will not survive credit.
Where is purpose-built student housing concentrated across Nottinghamshire?
Purpose-built student accommodation in Nottingham is concentrated in the city centre around Nottingham Trent University's City Campus, while Lenton and Beeston serve the University of Nottingham.
Nottingham city centre
Nottingham Trent University's City Campus anchors most of the student accommodation (PBSA) in Nottingham city centre. Island Quarter Phase 2B, a ten-storey 400-bed block, received full permission on 1 December 2025 (West Bridgford Wire, December 2025). The High Court dismissed Code Students' judicial review of the approval for a 610-bed Guildhall scheme in August 2026 (Solicitors Journal, August 2026). Code's own 1,252-bed all-studio Glasshouse Street scheme was refused in December 2025, with an appeal inquiry expected in early 2027 (GSL, July 2026). The council reports about 225 units under construction at Corner Point on Huntingdon Street (Nottingham City Council, March 2026).
Lenton
The principal University of Nottingham student suburb between the city and University Park. Its terraces are mostly houses in multiple occupation (HMOs), which the Article 4 direction now controls, so new student housing here is rare.
Beeston
South-west of University Park, in Broxtowe borough rather than the city. The 419-studio Beckton House next to Beeston tram stop was completed for the 2026/27 year (Build News, September 2026).
Arboretum and Radford
North and west of NTU City Campus, mixing student terraces with older purpose-built blocks that now compete directly with new supply on rent.
Clifton
Home to NTU's Clifton Campus in the south of the city, a smaller and more self-contained student market.
How does the City of Nottingham control new PBSA?
Local Plan policies HO5 and HO6 require robust, site-specific evidence of need for new PBSA. The council wants cluster-led schemes, with studios no more than 20% of bedspaces, and has put its draft PBSA supplementary planning document on hold. A permanent direction restricting "To Let" boards across nine high-student areas took effect on 30 March 2026, and the council is consulting on guidance for converting PBSA to co-living (Nottingham City Council, March 2026). A city-wide Article 4 direction has required planning permission to convert a family home into a small house in multiple occupation since 2012 (Nottingham City Council).
In practice, a new all-studio PBSA scheme faces a hard case for planning permission, and new supply is slowing. The council expects up to 663 new bedspaces for 2026/27, against an average of 2,086 a year over the previous five years, with about 5,500 permitted or likely to be permitted (Nottingham City Council, March 2026).
Financing student accommodation in the East Midlands
In a market adjusting to new supply, much of the funding need is for existing buildings: stabilisation for recently completed schemes that have not let fully, refinance of maturing loans on lower valuations, and investment and refurbishment finance for buyers repositioning older stock. Unite said its new openings in 2025 were 65% occupied on completion and that Nottingham was particularly affected by new supply that year (Unite Group, 2025 results). Development finance is still possible for a well-located, cluster-led scheme with clear evidence of need.
- Occupancy. Lenders size investment debt, typically 55 to 65% LTV, on collected rent and current occupancy, not on the business plan.
- Room mix. Studio-heavy schemes carry the highest vacancy in the council survey and face the 20% studio cap. Cluster flats with good social space let better.
- Pricing position. Rents benchmarked against the falling entry level, not the top of the range.
- Time to stabilise. Stabilisation facilities of 12 to 36 months, long enough to cover a second letting season.
All lending is subject to status, valuation and lender criteria. We are a finance arranger and introducer, not a lender. Nearby markets: Derby, Birmingham and Coventry.
Questions
What is classed as purpose built student accommodation?
Is Nottingham oversupplied with student accommodation?
Is purpose-built student accommodation in Nottingham a good investment?
Can I get planning permission for a studio scheme in Nottingham?
- Nottingham City Council, Student accommodation update report (March 2026)
- Nottingham City Council, Planning for student accommodation
- HEPI, Martin Blakey, What's happening with the UK's student accommodation? (April 2026)
- Unite Group, 2025 preliminary results
- Knight Frank, Student Accommodation Outlook 2025/26
- West Bridgford Wire, Island Quarter student tower with 400 beds approved (December 2025)
- Solicitors Journal, Code Students v Nottingham City Council (August 2026)
- GSL, Code challenges rejection of £150m student scheme in Midlands (July 2026)
- Build News, Winvic completes 419-studio student accommodation scheme in Beeston (September 2026)
 Written and reviewed by Matt Lenzie, Founder and principal. Last reviewed .